Macro, Inflation & Rates
Twice a month, one note on the macro picture in the United States and the euro area: growth and the labour market, inflation, and what the Fed and the ECB do next. Each edition sets our view against what markets price, so you see where the two differ and what would close the gap. The edition before the US inflation release adds our forecast for it, against consensus.
The models behind this research: GDP and inflation nowcasts and Central bank assessment.
Part of the Macro bundle.
Structure
What's inside
- Executive summary: the conclusions up front, and one table that sets the United States and the euro area side by side.
- United States: growth and the labour market, inflation, and what we think the Fed does against what markets price.
- Euro area: the same three questions for the euro area and the ECB, kept apart from the United States.
- Inflation preview: in the edition before the US inflation release, our forecast against consensus and the items that could surprise.
- Sectors: what equity leadership says about the economy, set against the jobs data.
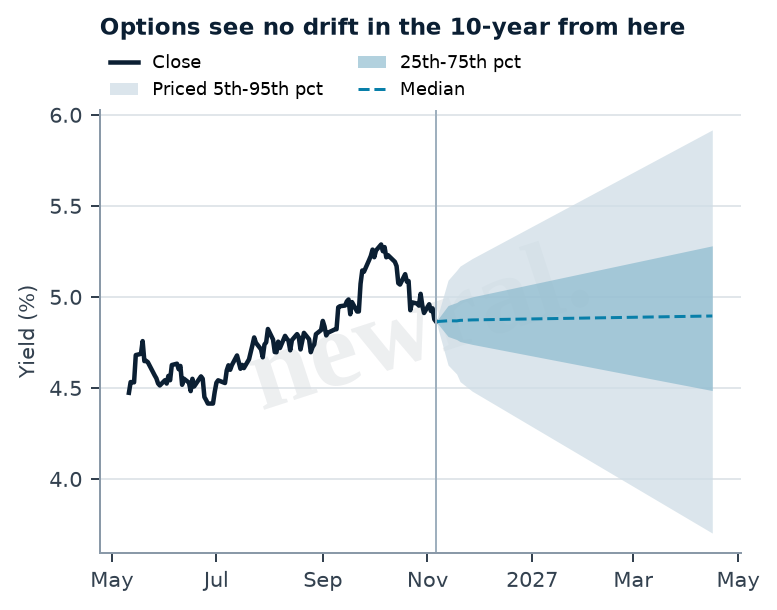
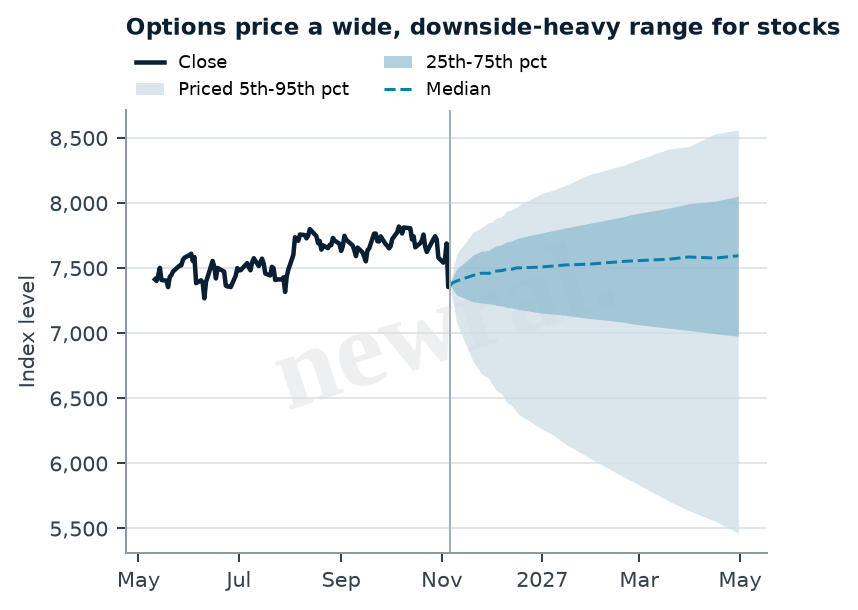
- What markets price: the ranges options price for bond yields and equities.
- The next two weeks: the releases and meetings that matter, and what would move our view at each.
- What would change our view: the outcomes that would make us think again.
Example excerpt · November 2026
The data never joined the sell-off
Key messages
- Markets priced a US growth scare over the past two weeks that the data do not show, and we side with the data. Jobs, surveys and our nowcast all firmed while bonds rallied, so we think the 10-year is likelier to end the month in the upper half of the range options price.
- Fed: we think the Fed hikes by a quarter point on 9 December; markets put the chance of a hike at about 78%. A hike would barely move the 2-year; a hold would, and after Friday's jobs report we think markets leave too much on one.
- ECB: we think the ECB hikes on 17 December and then pauses; markets price a little over a 72% chance of the December move. Rising services inflation outweighs softer surveys, but their job cuts argue against a second hike.
- US equity leadership is pricing an industrial slowdown that factory jobs and surveys contradict.
From the executive summary
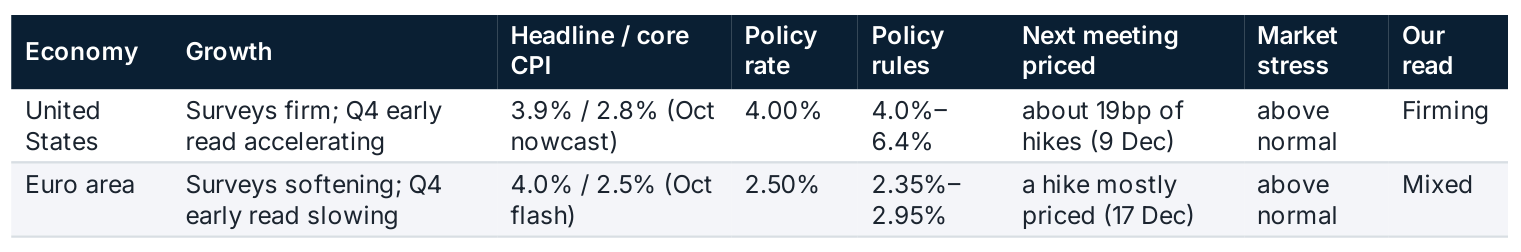
Every edition opens with one table that sets the two economies side by side: growth, inflation, policy and what markets price for the next meeting.
Sample note
Request a sample note
Tell us a little about yourself and we will send a recent note to your inbox.